The Number One Enemy of Your Retirement Savings!
Wednesday, March 08, 2023
Modern Enemy Number 1-Devastating Healthcare Costs!
In 2015, the Kaiser Family Foundation found that medical bills made 1 million adults declare bankruptcy. In 2017, Debt.org found that people aged 55 and older account for 20 percent of total filings.
In fact, the above statistic may be a little low. According to Muriel Gillick’s recent book, The Denial of Aging: “The latest prediction is that if you are just now turning 65, you have nearly a 50 percent chance of spending some time in a nursing home before you die. Approximately 10 percent of those nursing home stays will be short-term, intended for recuperation after a hospitalization. The remainder will be for the long haul, with discharge to a funeral parlor, not to the family home.”
And as the proportion of us reaching 65 increases, the cost of providing healthcare for an older American is three to five times greater than the cost for someone younger than 65. As a result, by 2030, the nation’s healthcare spending is projected to increase by 25 percent.
Medicare spending has grown about nine fold in the past two decades, from $37 billion in 1980 to $336 billion in 2005 (according to the Center for Disease Control’s “The State of Aging and Health in America,” 2007).
The Medicare Gap!
The problem is that Medicare spending, even though it is increasing to cover the increased costs of many illnesses, does not cover certain illnesses at all. Many Americans are under the false and dangerous assumption that the costs of their healthcare once they reach age 65 will be covered by Medicare. Not true! The chart below shows the illnesses (in green) that are typically covered by Medicare and the illnesses (in red) that are likely to break the family bank because the cost of long-term care that are often required by these illnesses are not covered by Medicare.
Medicare does provide some coverage for long-term care in the event you or a family member contracts one of the diseases in red above. However, the costs that Medicare will cover are extremely limited. Medicare will only pay for up to 100 days in a skilled nursing facility, and then after that you are on your own. So, for example, if you had a stroke and needed long-term convalescent care either at home or in a nursing facility, the costs for such care would not be covered by Medicare.
Who Pays?
Who would cover the costs of care in such a circumstance? Well, if you were fortunate enough to have purchased long-term care insurance, then it may pay for a portion or even all of the care. However, in my experience long-term care is often inadequate in paying for long-term care.
For example, when my mother contracted a devastating and debilitating illness 15 years ago I went out and purchased the best long-term care policy I could get. At the time it covered the full cost of care in all three long-term care scenarios (btw, if you don’t know what the three scenarios of long-term care are it is important you find out). Even with the best inflation protection I could purchase the policy now only covers about 70% of the cost, and I calculate that by the time I may need the policy in 25 years I will be LUCKY if it covers 25% of the cost due to the fact that health care costs are rising much faster than my inflation protection. In fact, I estimate that at the current rate of increasing costs I will have a $25,000 per MONTH SHORTAGE in my policy!
As you can see, even people with the best long-term care insurance are exposed.
If you don’t have long-term care insurance, then you would pay out of your pocket until such time that you were sufficiently impoverished so that you could qualify for assistance under another government program called Medicaid (Medi-Cal in California).
Medicaid is a combined federal and state program that will pay for some of the healthcare costs of the poor. That’s right: You have to be poor with a maximum allowable income and/or assets to qualify for assistance under Medicaid.
The Good News!
But wait. That is only half of the story. The good news is you don’t have to go broke to qualify for Medicaid. The state divides assets into exempt and non-amount of exempt assets and you can have an unlimited amount of exempt assets!
The Bad News!
Very often when we need to do Medi-Cal planning to qualify you or your spouse (or you if single) there is a mental defect that has occurred. Dementia, Alzheimer’s, stroke or something else that causes what is known as “legal incapacity.” If you have a legal incapacity you do not have the legal capacity to sign documents authorizing us to move assets from the “non-exempt” to the “exempt” category so you can qualify under the law. The Department of Health Services could prosecute you or whoever attempted this on your behalf for fraud.
More bad news! In my experience, at least 90% of the trusts and powers of attorney’s that I see people bring into my office are what I call “death trusts”. They do not have the necessary language that gives someone else the authority needed to do planning for you (your spouse, a child, or family member). And if it is not in your documents now, we can’t put it in your documents after you have lost legal capacity! Your documents (trusts and powers of attorney) must include what I call Medicaid Triggers in order for us to do planning when needed. If not, we can go to court and beg a judge to allow us to do what we could have done privately, for a lot less money. And by-the-way, there is no guarantee a judge will approve your request.
Bad Solution
So should you give away all your assets to your children so you are technically broke and hope your children will take care of you when the time comes? If you do you could be costing them hundreds of thousands of dollars in capital gains taxes, not to mention that this could disqualify you from receiving Medicaid at all!
The Modern Asset Protection Trust (M.A.P.T) TM
At Youngman Ericsson Scott, LLP, we’ve developed the Modern Asset Protection Trust.TM This trust and its related documents (financial powers of attorney) have all the necessary language to allow us to do planning if needed. Even more importantly, they have a trust protector, to make sure your documents can be modified to keep current with the rapidly changing laws. But modern documents are only part of the solution. Keeping your plan up to date, and you and your family educated and trained is even more important.
Just the F.A.C.T.S.TM
That is why we have developed the Family Awareness Comprehensive Training System (F.A.C.T.S.).TM Unlike many estate plans that are drafted and put in a file cabinet or safe, never to see the light of day until your family pulls them out to see they don’t work, we have developed a system to automatically keep you, and your family, current, trained and aware. We provide online education and training to you, your family and anyone else who needs to know about your plan. We show them what to do when, and we don’t nickel and dime you with hourly fees. For members of our F.A.C.T.System, we automatically keep your plan up-to-date, and your family educated on what to do when. It is a radical new way of bringing the dusty old legal industry into the 21st century, and I am not aware of another program like it in the country.
Because of what my family went through, I never want another person or family to go broke because of healthcare costs. It can be prevented, but you must empower yourself and your family now before there is a need.
For those of you who have attended my workshops you know I speak of six (6) modern enemies of family’s wealth. This was enemy number one (1). Enemy number two (2) may be even more overlooked!
Hi, I'm Reed Scott
Founder of Modern Asset Protection Planning
Modern Asset Protection Planning (MAP Planning) is the holding company for all our asset protection and wealth creation systems. Within Map Planning is the Scott Law Group, Scott Wealth Advisors and our many products and resources including "Estate Planning is Dead," The Attorney's Guide to Tax Free Long-Term Care, and the Business and Professionals Asset Protection Guide. Our blog will contain articles of interest to families, professionals and business owners whether you're concerned about reducing taxes, asset protection, wealth creation, retirement, and occasionally a topic that I just thought you'd find interesting. For more realtime content I encourage you to join our Facebook Communities: For Families we have new content every week at the "Estate Planing is Dead" Group here:
For Business Owners and Professionals we have new content on reducing taxes, selling a business, asset protection, retirement planning and everything else related to your business at our Facebook Group "The Business And Professionals Assert Protection Group." here:
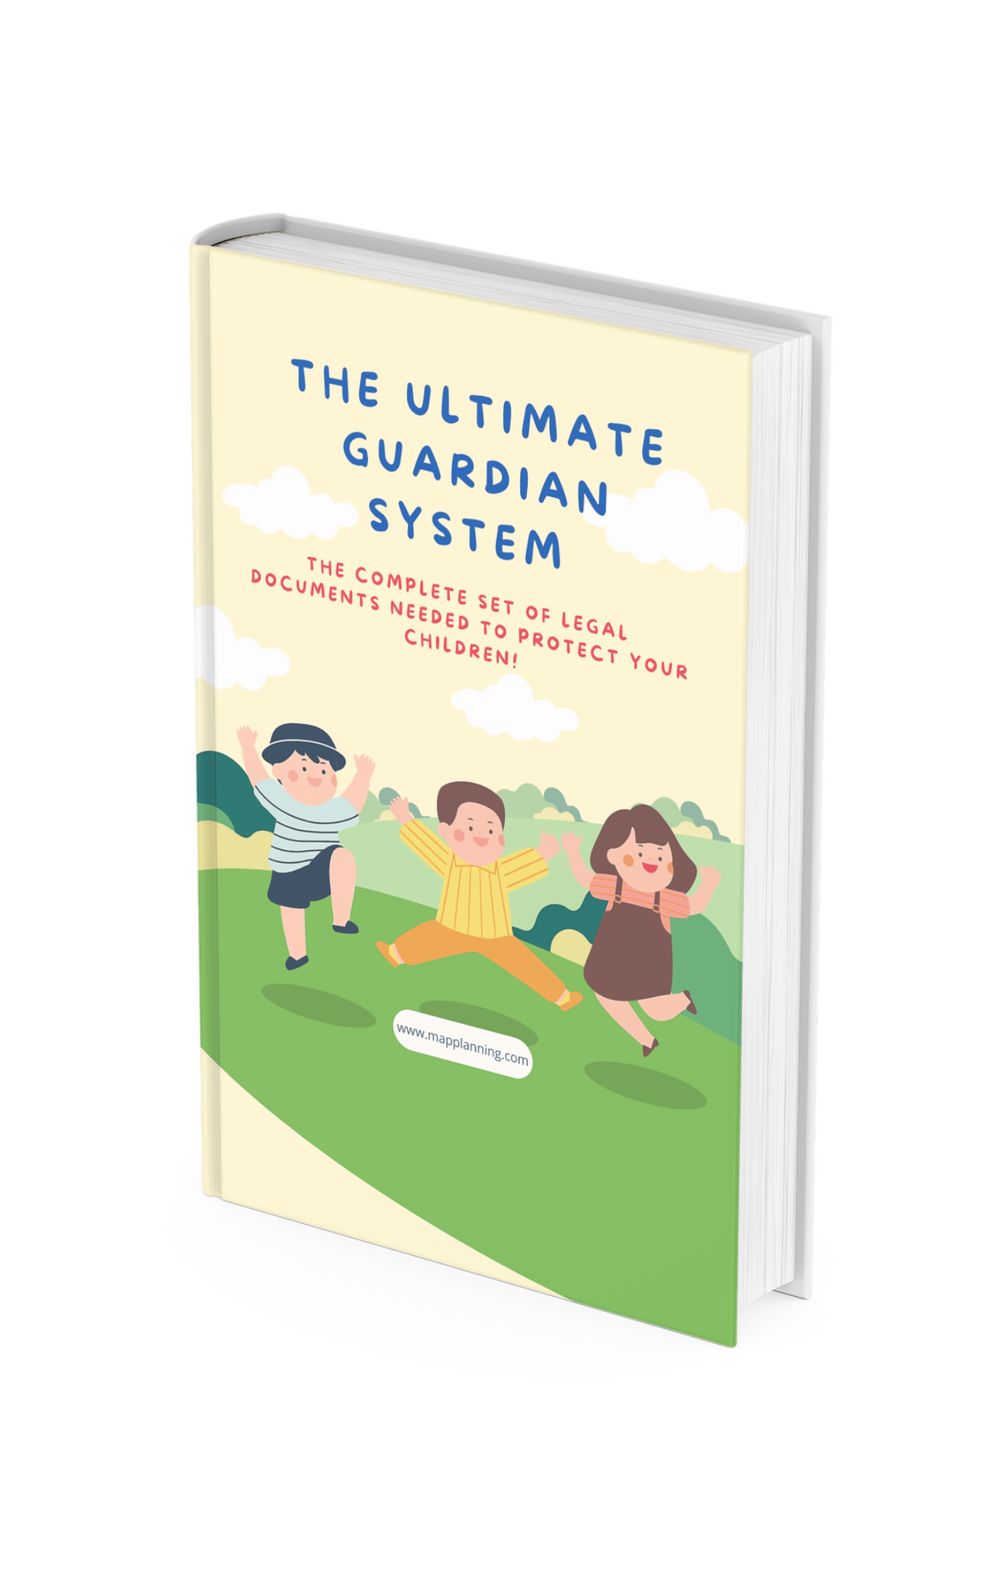
Get Our Complete Child Protection System Today!
Super excited about this product? We are too. We think there are so many young families that put off doing this important planning to save money that we created this low cost solution to an attorney. If you your adult child hasn't done this for your grandchildren this package would make a great gift!
Ready to buy it? Get access to the Product here:
Pages
Social